
11 Reasons Why Your Home Warranty Claim May Be Denied (And What to Do)
MARCH 09, 2026 | Home Care Buzz Experts | 10 minute read
Blog Summary
Discover the top reasons why home warranty claims are denied, and how to avoid common pitfalls.
Explore popular misconceptions about home warranty exclusions and plan cancelations, so you can get the most from your coverage.
Was your home warranty claim denied? Like any warranty, a home warranty has terms and conditions that must be followed for coverage to apply. While most home warranty claims are approved, a few are denied — and in certain cases, your plan can be canceled. Knowing the reasons why can help you avoid surprises and make the most of your home warranty coverage. Read on to learn more about home warranty exclusions and why a claim could be rejected.
What’s the Difference: Home Warranty Claim Denied vs. Canceled
When a home warranty is canceled, your coverage ends, and you can no longer file claims. When a claim is denied, only that particular service request is rejected — you can continue to use your home warranty as you normally would for any future covered breakdowns.
Home warranty claims from First American are not often denied. In fact, we approve more than 96% of claims that our members submit.* When a home warranty claim is denied, it’s usually because of a misunderstanding about how home warranty coverage works or what appliances and systems are covered under a particular plan.
Here are a few examples of common things people (mistakenly) believe about home warranty coverage:
-
I’ll try to fix it, and then if I can’t, I’ll call my home warranty company.
-
I can find a service technician on my own and then send the bill to my home warranty company.
-
A home warranty will cover anything that happens to my covered appliances and systems.
-
A home warranty covers everything in my home.
Here’s how a First American home warranty works:
-
When a covered item breaks, submit a service request right away, either online or via phone.
-
We’ll assign a prescreened technician who will contact you to schedule an appointment.
-
The technician will diagnose the problem, confirm that the broken item is covered, and then repair it. If it can’t be repaired, we’ll replace it.**
A home warranty covers many major appliances and home systems when they break, but it doesn’t cover everything in your home. Learn more about what you can protect with a home warranty, and what’s not covered by a home warranty.
Home Warranty Plan Canceled? Learn Why
Although it’s not common, your home warranty coverage can sometimes be canceled. This usually happens for two reasons:
- Failure to pay
- Misrepresentation
While not paying the contract fee is self-explanatory, misrepresentation is a little more complex. Often, people don’t intend to give false information about their home; they simply select a plan that wasn’t designed for their home or needs. Or they run a home-based business that a home warranty won’t cover. Here are some examples:
Home Warranty Plans for Your Home Type
Home warranties offer protection for most types of homes. However, some homes, such as very large homes or those with multiple units, such as duplexes, require different coverage. If you choose a home warranty for a smaller home but yours is over 4,000 sq. ft., this would be considered a misrepresentation.
That’s why it’s important to select a plan that fits your home’s specifications. If you aren’t sure which home warranty plan is right for you, we can help you choose the coverage that best fits your needs.
Related: What home types does a warranty cover?
Home Warranties Don’t Cover Businesses
Do you use your home for a business such as a daycare, care home, or short-term rental? If so, a home warranty will not cover that home. However, a home warranty can cover long-term rental properties. Additionally, if you don’t disclose that the home is used for non-covered business, like a daycare or short-term rental, your policy will be canceled for misrepresentation.
Getting Coverage: What to Know
The table below provides details on home type, use, and size, and how that information affects whether First American Home Warranty can provide coverage:
| Covered | Can Be Covered | Not Covered | |
|---|---|---|---|
|
Home Type |
Single-family homes, condos, townhomes, or mobile homes. |
Multiple units, guest homes, other structures |
Commercial property |
|
Home Use |
Owner-occupied or long-term rental |
N/A |
Business uses include:
|
|
Home Size |
4,000 sq ft and under for homeowners. 5,000 sq ft and under for buyers and sellers. |
Over 4,000 sq ft for homeowners Over 5,000 sq ft for buyers and sellers |
N/A |
Reasons Why Home Warranty Claims Are Denied
As mentioned, the majority of home warranty claims are approved without issue. Here are some of the reasons why 4% of First American home warranty claims are denied:
1. You Try to Fix It Yourself
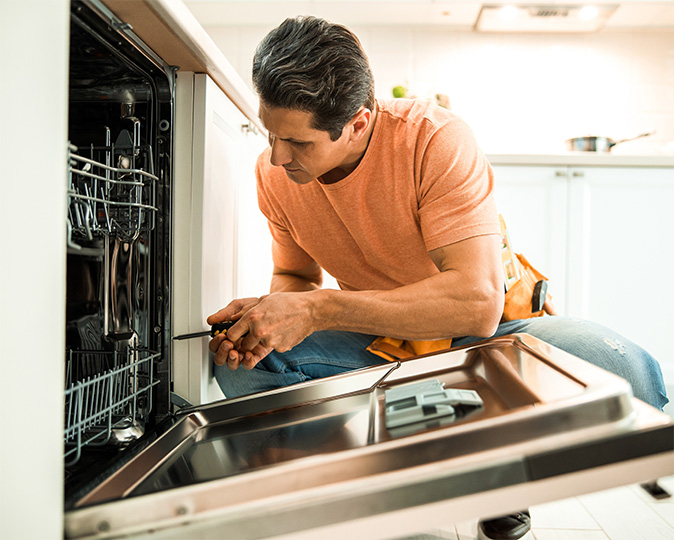
DIY solutions are often a great way to solve simple problems and save a little money. But if the item is covered by your home warranty, don’t try to fix it yourself. It might seem like it would be faster to watch a video online and quickly take care of the job. And sometimes, that’s ok. But if the issue differs from what you expected, or it turns into a more complex job, you have a bigger problem.
For example, let’s say your dishwasher breaks, and you think you can fix it. You disconnect it and start working on the issue. But then things get complicated, and you need help. You call your home warranty company to take care of it, but your claim is denied.
Here’s why: To diagnose a dishwasher correctly, the technician needs it to be properly installed in your kitchen. Otherwise, they will have to reassemble and reinstall the dishwasher, which isn’t covered by a home warranty.
Instead, take full advantage of your home warranty and contact us first. If you’re not sure an item is covered, reach out to us, and we’ll let you know. Or you can go online and check your plan’s specific coverage details.
Bottom line: A First American home warranty is designed to give you peace of mind by covering appliances and systems when they break due to normal wear and tear. It doesn’t cover items that are uninstalled, disassembled, or missing parts.
2. You Use Your Own Service Technician
If you’ve never had a home warranty, you might think you can call any contractor and your home warranty company will reimburse you. However, First American home warranties work differently. With our coverage, you simply submit a service request either online or via phone, and we take care of the rest. We’ll assign a prescreened technician from our network who will set up an appointment with you to begin the repair or replacement.
3. Accidents or Misuse
A home warranty covers normal wear and tear from everyday use. It doesn’t protect against accidents or misuse, like:
- Accidentally bumping into your outdoor AC unit with a lawnmower
- Pulling the handle off your microwave, fridge, or oven
- Dropping toys or keys down the toilet
If you filed a claim for these types of situations, your home warranty would deny the claim, as accidents are not covered. Nor is using an appliance or system in a way it isn’t designed for, such as:
- Using the open dishwasher door as a step stool
- Placing a baking dish filled with food on the open oven door
4. Other Types of Damage
Additional home warranty exclusions that are not considered “normal wear and tear” and are therefore likely to be denied include:
- Outdoor AC unit struck by lightning or damaged by snow or hail
- Frozen pipes that burst
- Appliances damaged by power surges
- Home systems and appliances damaged by a house fire
- Items that are stolen from your home
Your homeowners insurance typically covers damage and loss resulting from natural disasters such as fire, floods, or storms. It’s always a good idea to review your home warranty coverage alongside your homeowners insurance policy so you can become familiar with what each covers. Home warranties and homeowners insurance can complement each other, and many people have both as part of their home protection plan.
Learn more about what homeowners insurance covers vs. a home warranty.
5. Stolen Items
Strange as it sounds, residential copper pipes and HVAC units get stolen. A home warranty, however, covers broken items — not stolen ones. Your homeowners insurance may be able to help cover these types of losses.
6. Lack of Capacity
When you add or upgrade home systems and appliances, make sure your home has the electrical, plumbing, and other capabilities to handle the new equipment. For example, if you add a second air conditioning unit or refrigerator and your electrical panel doesn’t have enough capacity, this could cause electrical problems. These electrical problems wouldn’t be covered by a home warranty.
7. Mold and Hazardous Materials
A home warranty doesn’t cover mold in your home. However, if you have a leaky water pipe that may be causing moisture to build up, a home warranty can fix the covered plumbing issue before it leads to mold.
A home warranty also doesn’t cover hazardous materials, such as asbestos. This material was used in many building products, including roofing, flooring, drywall, and ductwork. If your home’s HVAC ducts break, for example, and they contain asbestos, your home warranty company will deny your claim. Asbestos must be handled by professionals with special training and certification.
8. Pests
Some home warranty plans can cover pest removal, including roaches, mice, and more. However, if pests are left unchecked and ruin an appliance or system, repairs won’t be covered — for example, pests eating electronic components or control boards in appliances, or mice nesting in pool motors and equipment.
Related: Does a home warranty cover termites?
9. Not Contacting Us Promptly
If a covered appliance or home system breaks and you don’t contact your home warranty company until after your plan expires, it won’t be covered. Request service promptly when something breaks, and remember to renew your home warranty annually. Better yet, set your coverage to renew automatically.
10. Dishonesty
A home warranty covers items in “good, safe working condition” when the home warranty contract begins. If the condition of an appliance or home system is misrepresented as being in good, safe working condition when purchasing a home warranty, yet it actually isn’t, any claim relating to that item will be denied.
For example, if you buy a home warranty and immediately file an HVAC home warranty claim for a system that broke before your coverage began, your claim would be denied. The technician would be able to determine that the unit hadn’t been operational for quite some time.
Some home warranties have a short waiting period after which you can start requesting service, and you must honor that waiting period. Regular maintenance can help your appliances and systems stay in good working order longer.
11. Improper Installations and Modifications (Sometimes Covered)
Home warranty companies typically define improper installation as "not done to manufacturer specs or building code." For example:
- Plumbing: In older homes, copper piping is sometimes connected directly to galvanized pipes. If the joint isn’t connected correctly, the pipes will corrode quickly.
- AC systems: An outdoor AC unit installed on a sloped or uneven surface may become leaky.
Some home warranty plans will cover improper installations and modifications if a failure is found during a home inspection. First American’s Essential and Premium plans for homeowners include add-on coverage for code upgrades and permits, as well as for improper installations, modifications, and repairs. Home buyers and sellers can also add plan options for extra protection to help cover these circumstances.
Related: How to file a home warranty claim.
Making the Most of Your Warranty
These tips can help you to fully benefit from your home warranty protection:
- Choose the right level of home warranty coverage. When you buy a home warranty, choose a plan that covers your home’s specific systems and appliances. First American Home Warranty offers a variety of plans, coverage options, and upgrades to help you get the level of protection you need.
- Know what your home warranty covers. If you have a First American home warranty, it’s easy to sign into your online account and check your coverage and home warranty exclusions.
- Contact us first when something breaks. Learn more about how the home warranty service process works.
- Renew your home warranty annually. Protect your budget from costly, unexpected repair and replacement bills when covered home appliances and systems break.
FAQs on Home Warranty Claims
Why would a home warranty claim be denied?
A home warranty covers appliances and systems that break due to normal wear and tear. It doesn’t protect against accidents or misuse; for example, using the item in a way it wasn’t designed.
What should I do if a home warranty company denies my claim?
If your claim is denied, reach out to your home warranty company to ask for clarification on how the determination was made.
Can I dispute a home warranty denial?
If you feel your home warranty company should cover your claim, contact them for an explanation. Usually, a quick review of your coverage can help sort out any misunderstandings and provide a clearer understanding of what’s covered, along with home warranty exclusions.
Can a home warranty company deny a claim for lack of maintenance?
Not usually. First American home warranty plans cover appliances and systems that fail from lack of maintenance. However, these items need to be in good, safe working order at the time your coverage begins. But it is important that the customer maintains their systems so that they run efficiently.
Will a home warranty cover an appliance or system that is already broken?
First American will not repair or replace items that were broken prior to the start of your home warranty coverage. However, some plans purchased as part of a real estate transaction can offer some protection against unknown pre-existing conditions — if, at the time coverage begins, the defect is not known or could not have been reasonably observed by inspecting or operating the system or appliance.
*Based on 2025 claims that were fully denied.
**In some instances, Homeowner and First American may agree to payment of cash in lieu of repair or replacement. Payment will be made based on First American’s negotiated rates with its suppliers, which may be less than retail. Please review the sample contract for specific coverage, terms and limitations.


Keep Reading




Home Care Buzz Experts
The First American Home Care Buzz team is made up of experienced home warranty writers and editors. Our team provides valuable insights and information to help homeowners like you meet the daily challenges of homeownership.
This article is about...